

Quick Loan Calc
by Saifidev
3.4
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 3.4
- Price
- Free
- Download
- 500.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
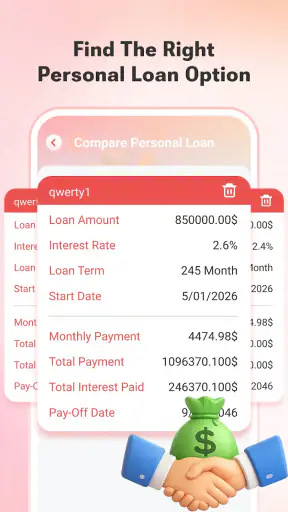
 Analysis by Getfullapps
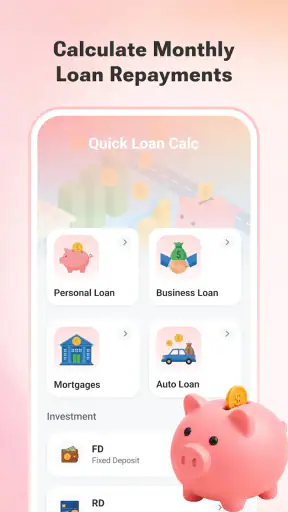
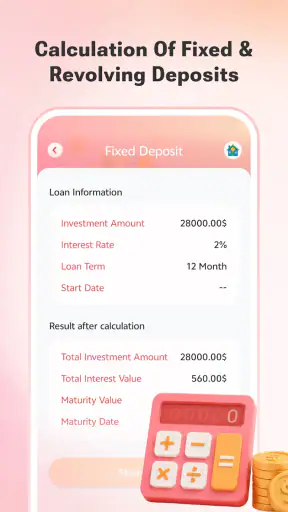
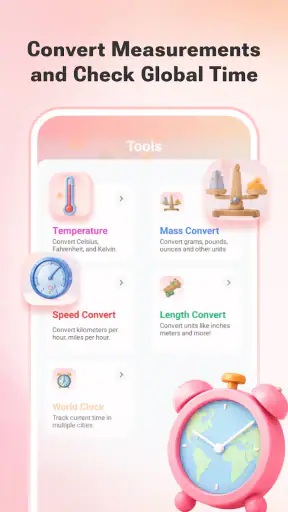
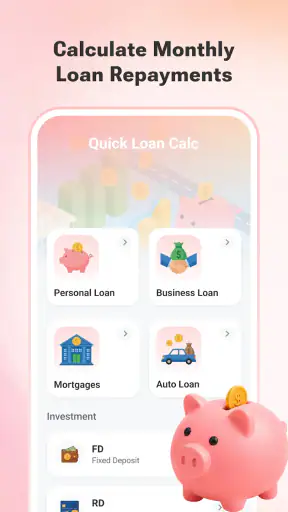
I installed Quick Loan Calc to see whether it could make everyday borrowing calculations less confusing, and I found an app with a deliberately narrow purpose. It brings a loan calculator, a unit converter, and a world clock into one finance-focused tool. That combination is more practical than it first sounds: when I am checking a possible repayment, comparing figures in another unit, or coordinating with someone in a different time zone, I can stay in one lightweight utility instead of switching between several apps.
The app is free, developed by Saifidev, and aimed at Everyone. Its current version is 1.0.0.8, and it works on Android 8.0 or later. At the time of writing, it has passed 500 thousand installs and holds an average rating of 3.4 from roughly 411 ratings. Those figures suggest that it has attracted a meaningful audience, but the middling score also tells me to approach it as a useful calculator rather than a polished replacement for a full banking or lending service.
From a borrowing question to a usable answer
I start with the moment this app is most useful: when a borrowing idea is still a question, not a commitment. I’ll look at how its calculator can turn that question into a working estimate, while keeping the assumptions clear enough to check before acting.
The starting condition: a quick estimate before making a decision
The most natural reason to open this app is a simple question: “If I borrow this amount, what might the repayment look like?” I would use it before contacting a lender, while comparing informal offers, or when checking whether a proposed payment fits into my monthly budget. It is especially useful at the early stage, when I need an estimate quickly and do not yet want to complete an application.
That distinction matters. A calculator can help me understand a number, but it does not decide whether a loan is affordable, suitable, or safe. I still need to check the lender’s terms, fees, penalties, eligibility rules, and repayment schedule. I would treat the result as a planning aid, not as an approval promise or a formal quotation.
In a realistic situation, I might be sitting at home comparing a small personal loan with an offer discussed by a local provider. I can enter the figures, inspect the result, and then write down the amount I want to verify. The value is in reducing mental arithmetic at the point where a rough estimate can prevent an impulsive decision.
Step one: entering the loan details carefully
The first useful habit is to prepare the figures before opening the calculator. I would have the principal, interest information, and repayment period ready, along with any known charges. If I enter incomplete or misunderstood terms, the output may look precise while still being irrelevant to the actual offer. The app can process inputs; it cannot correct a lender’s wording for me.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
I also recommend testing the calculation with more than one repayment period. A shorter term may increase the regular payment but reduce the time spent repaying, while a longer term may appear easier each month and cost more overall. Looking at both outcomes gives the calculator a more meaningful role than entering one set of numbers and accepting the first answer.
One non-obvious use is to calculate a payment ceiling before shopping for a loan. Instead of starting with the maximum amount someone is willing to lend, I can begin with the amount I can realistically handle, then work backward. That approach keeps the tool connected to my budget rather than turning it into a way to justify the largest available borrowing amount.
Step two: checking the result instead of trusting it blindly
After entering the details, I would read the result as an estimate and check whether the assumptions match the real offer. Loan calculations can differ depending on whether interest is described as flat, reducing-balance, annual, monthly, or effective interest. Fees may also be added separately. If the lender uses a method that does not match the calculator’s input structure, the displayed figure may not be comparable.
This is where the app’s simplicity is both a strength and a limitation. A focused calculator is less intimidating than a full financial suite, but it may leave more interpretation to the user. I would never compare two results until I had confirmed that both use the same interest convention and repayment frequency.
A practical checking method is to repeat the calculation with a small change in one input. If changing the term produces an unexpected movement in the payment, I would stop and inspect the entries rather than assuming the app is wrong. This sensitivity check is helpful because it catches misplaced digits, an incorrect unit, or a period entered in the wrong format.
Step three: using the converter when the numbers do not match
The unit converter becomes useful when the figures involved are expressed differently. For example, a budget may be discussed in one currency while a product price, distance, weight, or measurement appears in another unit. I would use it as a supporting step before placing values into a calculation, especially when a quick conversion prevents a basic comparison error.
This is not the same as a complete financial exchange service. A conversion result should not automatically be treated as a live market quote or a final amount for a payment. When money is involved, I would verify the relevant rate and any fees through the provider that will actually process the transaction.
The useful workflow is to convert first, record the converted figure, and then enter it into the loan calculation only if the units and currency assumptions are genuinely compatible. Mixing a converted amount with a lender’s separate fee structure can create a misleading result. The app helps with the arithmetic, but I remain responsible for keeping the inputs consistent.
Step four: using the world clock as a coordination tool
The world clock may seem unrelated to borrowing, but it can help when a financial conversation involves someone in another country. I might need to contact a lender, family member, employer, or business partner at a reasonable local time. Having the time-zone check beside the calculator reduces one small but real source of friction.
I would use the clock before sending a message or arranging a call, particularly when a repayment question needs confirmation from another person. This is a modest feature, but it supports the complete workflow: calculate privately, convert figures if needed, then coordinate with the person who must confirm the next step.
It is also a reminder that the app is designed as a compact collection of utilities rather than a dedicated lending platform. The three tools support adjacent tasks, but they do not form a connected loan application process. I should expect to carry information from one part of the workflow to another myself.
The handoff: moving from calculation to a real lender
The most important handoff happens when I leave the app and speak to the lender or provider. I would copy the key figures into a note, including the amount considered, the proposed term, the estimated payment, and any assumptions used. Then I would ask the provider to confirm the official repayment schedule and total cost.
This manual handoff is not necessarily a flaw; it is simply part of using a standalone calculator. Still, it creates room for transcription mistakes. I would avoid relying on memory, especially if I have compared several scenarios. Writing down each scenario with clear labels makes it easier to notice when a lender’s official quote differs from my estimate.
Another useful handoff is from the calculator to my household budget. A payment should be tested against regular income and unavoidable expenses, not just against an optimistic month. I would also consider irregular costs and emergency savings before treating the result as affordable. The app can show what a payment might be, but only a broader budget can show whether that payment belongs in my life.
What the result is good for
For me, the strongest result is a clearer starting point. I can turn a vague borrowing idea into a few comparable scenarios and identify questions that need answering. That is valuable when I am trying to avoid signing up for terms I do not understand.
The app is also convenient for quick checks because it combines the loan calculator with supporting utilities. I do not need a separate converter for every small unit question or a separate clock when arranging an international call. The tools are related enough to justify sharing space, even though they remain separate tasks.
Its free price makes experimentation easier. I can compare possibilities without first committing money to a specialist calculator. For a student, household planner, freelancer, or anyone checking a possible short-term expense, that low barrier is a genuine advantage.
At the same time, I would not use the result as the final word on affordability. The app does not replace a lender’s disclosure, a bank’s repayment schedule, or advice from a qualified financial professional. Its best role is the quiet preparation stage before a formal decision.
Where the flow breaks down
The workflow becomes less comfortable when the loan terms are complicated. Variable rates, irregular repayments, grace periods, insurance, late charges, and multiple administrative fees can make a basic calculation inadequate. If the offer contains several exceptions, I would move to a lender-specific calculator or a spreadsheet where each cost can be represented separately.
The same caution applies when accuracy must be documented. Someone preparing a business forecast, comparing detailed financing options, or keeping formal records may need a tool that explains its formula and preserves a history of scenarios. Quick Loan Calc is better suited to immediate checking than to audit-style financial work.
The 3.4 average rating also makes me temper my expectations about polish and consistency. I would test the app with simple, known examples before using it for an important decision. If the interface feels unclear or a result does not match an independent calculation, I would not force the workflow; I would switch to a more transparent alternative.
There is also a human limitation that no calculator fixes. A neat monthly number can make borrowing feel safer than it is. I would deliberately look at the total repayment, the consequences of missing a payment, and the reason for borrowing. If the loan is being used to cover a recurring budget gap, a calculator may reveal the problem rather than solve it.
Who should use it, and who should choose something else
I think this app suits people who want a fast, free way to explore straightforward loan scenarios and keep a few related utilities nearby. It is a sensible choice for early planning, casual comparisons, and everyday questions where speed matters more than advanced financial modeling.
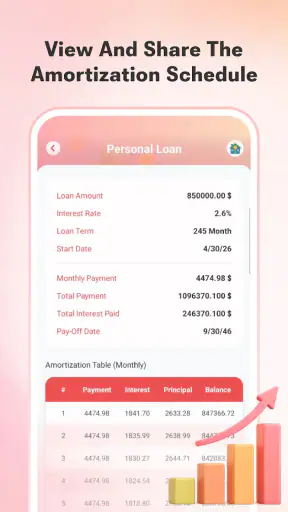
It is less suitable for anyone who needs lender-specific accuracy, detailed amortization analysis, saved financial records, or a complete application journey. A bank’s own calculator is usually the better option when I am already dealing with that bank, because its assumptions are more likely to match the actual product. A spreadsheet is better when I need to model changing rates, irregular payments, or a long list of fees.
I would also skip it as the sole tool for a major borrowing decision if I am unsure how the interest is calculated. In that situation, the right next step is clarification from the lender, not repeated experimentation inside a simple calculator.
My practical verdict after using the full workflow
Quick Loan Calc works best as a pocket-sized preparation tool. I can start with a borrowing question, calculate a few scenarios, convert supporting figures, check a time zone, and carry the resulting notes into a conversation with the relevant person. That end-to-end path is useful precisely because it stays simple.
Its simplicity also defines the boundary of my recommendation. I would use it to organize my thinking, catch rough affordability problems, and prepare better questions. I would not use it to replace official loan documents or to handle complicated financing without independent verification.
With over 500 thousand installs, the app has clearly reached many Android users, and its Everyone rating makes it approachable for general household use. Still, the average score of 3.4 encourages a careful trial rather than automatic trust. My advice is to test a straightforward example, compare the output with a calculation you understand, and then decide whether its workflow fits your needs.
My bottom line: this is a convenient free utility for quick loan estimates and nearby conversion or time-zone checks, but its value depends on disciplined input and sensible follow-up. If you want a fast first look before speaking to a lender, I would give it a try. If you need detailed financial modeling or an official repayment answer, I would move to a more specialized tool.
Pros
- Calculates loan payments quickly with minimal data entry.
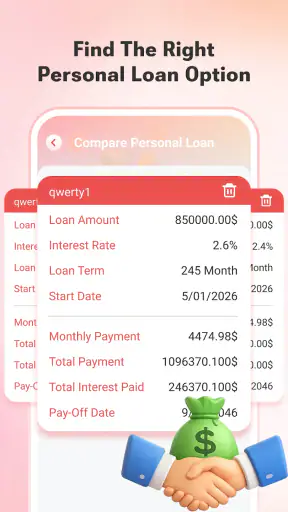
- Supports comparisons between different loan amounts and terms.
- Useful for estimating affordability before applying for credit.
- Simple interface is easy for first-time users to understand.
- Provides instant results without requiring an account.
Cons
- Results may differ from lenders’ figures due to fees or rounding.
- Does not approve loans or connect users directly with lenders.
- Limited value for complex loans with variable rates or irregular payments.
- Users must enter accurate interest rates for reliable estimates.
- May lack advanced tools for taxes, insurance, or extra repayments.
FAQs for Quick Loan Calc
What is Quick Loan Calc used for?
Quick Loan Calc is a financial calculator designed to help you estimate the cost of borrowing money. You can generally enter details such as the loan amount, interest rate, repayment period, and payment frequency to see an estimated installment and total repayment. It is useful for comparing scenarios, but it should not replace official figures from a bank or lender.
Can Quick Loan Calc calculate different types of loans?
The app can be useful for reviewing common loan scenarios, including personal loans, car financing, mortgages, or other installment-based borrowing, depending on the calculation options provided in the version you install. Results may vary based on whether the calculator supports simple interest, amortized payments, fees, or variable rates, so check the available fields before relying on an estimate.
Are the results from Quick Loan Calc accurate?
Quick Loan Calc can provide a helpful mathematical estimate when the information entered is correct, but its results may not exactly match a lender’s final quote. Banks and finance companies can include origination fees, insurance, taxes, penalties, changing interest rates, rounding rules, or additional charges. Always compare the app’s estimate with the official repayment schedule before accepting a loan.
Does Quick Loan Calc require an internet connection or personal information?
A basic loan calculator normally performs calculations directly on the device and may work without an internet connection. However, requirements can differ between Android and iOS versions, particularly if the app includes advertisements, cloud features, or links to financial services. Avoid entering sensitive information such as bank passwords, identification numbers, or account credentials unless the privacy policy clearly explains how that data is handled.
Is Quick Loan Calc suitable for making financial decisions?
Quick Loan Calc is best treated as an educational and planning tool rather than personalized financial advice. It can help you understand how loan amount, interest rate, and repayment duration affect monthly payments, making it easier to compare options. Before borrowing, review the annual percentage rate, total cost, fees, early repayment conditions, and your ability to meet every payment.

Quick Loan Calc
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via saifidev89@gmail.com, visit http://quickloancalcpro.com/, or review their https://sites.google.com/view/quick-loan-calc-privacy/.










